
Chapter 13 Lawyer Camden County
Top Bankruptcy Attorneys and Home Foreclosure Defense Attorneys.
Over 750 ★★★★★ Google Reviews
Contact Our Attorneys Today

EVALUATION
At Sadek Bankruptcy Law Offices, we realize that every situation is different. Our debt relief lawyers will take the time to learn about your situation and your goals. Our objective is to explain your legal options and offer the best debt relief strategy for you in the most compassionate and friendly manner possible. Call 24/7 to schedule your meeting with a lawyer.

AVAILABLE
Our office understands the financial stress our clients endure. Therefore, in addition to reasonable legal fees, we offer a payment plan to all of our valued clients to make quality legal services most affordable.

AND NJ
In addition to our primary law office in Center City, Philadelphia, we also have law offices throughout the Greater Philadelphia, Pennsylvania Area and in New Jersey. Our branch offices have contributed to making us the #1 Bankruptcy Filer and debt relief firm in the Greater Philadelphia area. Our goal is to have a convenient location within 20 minutes of where our clients work or reside.
Achieve Lasting Debt Relief by Filing Chapter 13 in Camden County
Are you suffering from mounting debt and want to regain control of your finances? Filing for Chapter 13 bankruptcy may be the solution you need. If you’re searching for an experienced and reliable Chapter 13 lawyer, Camden County, NJ, residents can trust the attorneys at Sadek Bankruptcy Law Offices.
We understand how overwhelming debt can be, and how difficult it can be to catch up on payments when you get behind. That’s why we’re so committed to helping you take back control of your finances and put your best foot forward. Our Camden County bankruptcy lawyers will work closely with you to create a repayment plan that fits your budget, address creditor actions, and protect what matters most to you.
Call (856) 890-9003 to schedule a free consultation with a bankruptcy attorney on our team regarding your case.
What Is Chapter 13 Bankruptcy?
Chapter 13 bankruptcy is a legal process that allows individuals to reorganize their debt and create a repayment plan based on their income and expenses. Chapter 13 enables debtors to keep their property while making affordable payments to creditors over three to five years.
This option is often used by those with regular income who want to catch up on missed mortgage payments, manage tax debts, or restructure other financial obligations. Our New Jersey Chapter 13 bankruptcy attorneys can help you understand your options and determine if Chapter 13 bankruptcy is right for you.

Posted on Google
 Edwin Maldonado2 November 2026
Trustindex verifies that the original source of the review is Google.
Great Bankruptcy Law Offices. I do recommend using them.Posted on Google Amir Tafreshi30 October 2026Very caring! Professional and knowledgeable. I would suggest Sadek law firm for anyone who is looking for solution to their financial problems.Posted on Google
 Korinna Jackson27 October 2026I would highly recommend Sadek Law for your bankruptcy filing. Brad was supportive and understanding of my situation when we first spoke about my potential case during my consultation and gave me great insight on how this could actually affect me in a more positive light than I first imagine. I went in no longer afraid of what this could mean for my future and my future credit. Then I worked for Jeanie as my filing attorney and she was amazing! I felt seen and she was so friendly and professional. She made sure I was ready and prepared for what was the next steps. Sadek Law made filing a breeze! I cannot thank them enough for helping me the way they did!.Posted on Google
 Suzette Stokes Anderson25 October 2026Outstanding legal service from start to finish! Knowledgeable, responsive, and extremely effective. They got the job done quickly and exceeded all my expectations. I wouldn't hesitate to use their services again or recommend them to friends and family.Posted on Google
 Daniel Selig6 October 2026John Idek and his staff were absolutely amazing. They were organized, attentive, and explained everything in terms I could understand. They made the whole stressful and upsetting situation as easy as possible! Highly recommend!!Posted on Google
 Jose Marmol5 October 2026I had a great experience working with Jeanie Wiesner on my Chapter 7 bankruptcy. She was awesome throughout the entire process and always stayed on top of my case. She was very responsive whenever I had questions or concerns and always returned my calls and emails. What I appreciated most was how friendly, polite, and professional she was. Bankruptcy can be a stressful process, but Jeanie made everything much easier to understand and made sure things were handled properly from beginning to end. I’m extremely happy with the service I received and would definitely recommend Jeanie to anyone looking for a knowledgeable, reliable, and caring bankruptcy attorney. Thank you, Jeanie!Posted on Google
 Kevin Valette2 October 2026The service provided was highly professional. They clearly possess great expertise and experience, are very honest, and I recommend them without reservation.Posted on Google
 Christopher Lake29 September 2026I could not be prepared for how incredibly easy a process bankruptcy was, and that was only the case because of how wonderful this law office is. I have a real chance at getting ahead in life now thanks to them, thank you so much.Posted on Google
 Mark McSpirit18 September 2026Sadek Law was amazing to work with. Very efficient. Jeanie Wiesner and the entire staff at the Mt. Laurel office were great. I would highly recommend Sadek Law.Posted on Google
 Hawkinsfamily HF17 September 2026Thank y’all so much appreciate all the help

Chapter 7 vs Chapter 13
In general, consumers tend to file for bankruptcy under either Chapter 7 or Chapter 13 of the United States Bankruptcy Code, depending on their income. Chapter 7 involves liquidating non-exempt assets to pay off creditors and completely discharge unsecured debts, such as medical bills and credit card debt. However, this type of bankruptcy is typically only available to individuals under a certain income level.
Chapter 13, on the other hand, allows individuals to create a more manageable payment plan to pay off debts over three to five years. This allows those with a steady income to catch up on secured debts like mortgages or car loans, all while keeping their assets.
Who Is Eligible to File Chapter 13 in Camden County?
To qualify for Chapter 13 bankruptcy in Camden County, an individual must have a regular source of income that can support a repayment plan. Their secured and unsecured debts must fall within certain limits set by federal law.
Additionally, the debtor must be current on their tax filings and cannot have had a bankruptcy petition dismissed within the past 180 days for failure to comply with court orders or appear in court. A bankruptcy attorney on our team can evaluate your financial situation and determine whether or not you are eligible for Chapter 13.
Who Is Not Eligible to File Chapter 13 in Camden County?
Those who are not eligible for Chapter 13 in Camden County are those with too much debt or too little income. If someone’s secured debts exceed the legal limit of approximately $2.75 million or if their unsecured debts surpass around $465,000, they will be deemed ineligible.
Additionally, if someone does not have a reliable source of income to fund a repayment plan, they will not qualify. Those who have had their bankruptcy petition dismissed within the past 180 days due to noncompliance with court orders or failure to appear in court are ineligible. Business entities like corporations or partnerships are also ineligible to file under Chapter 13, as it is reserved for individuals.
If you’re worried about being ineligible for Chapter 13 bankruptcy relief in Camden County, a bankruptcy lawyer at Sadek Bankruptcy Law Offices can help evaluate your circumstances and help you plan a path forward.
Why Might Someone File Chapter 13 Bankruptcy?
Someone might file for Chapter 13 bankruptcy to protect their home, car, or other valuable assets while managing overwhelming debt. This option is ideal for individuals with a steady income who need to catch up on missed mortgage payments or car payments, repay tax debts, or consolidate financial obligations into a single, manageable plan.
What Are the Benefits of Chapter 13 Bankruptcy?
Filing for Chapter 13 bankruptcy can provide a number of benefits, including:
- Protection from foreclosure and repossession
- Creation of a manageable repayment plan
- Retention of important assets like your home and car
- Stopping creditor harassment and collection efforts
- Discharge of remaining unsecured debts after the repayment period
- Opportunity to repay missed mortgage or car payments over time
- Protection for co-signers on certain consumer debts
- Restructuring of secured debts with potential adjustments to terms
By choosing Chapter 13 bankruptcy, you can take control of your finances while working toward a debt-free future. If you’re ready for a fresh start, call Sadek Bankruptcy Law Offices to discuss your debt relief options with an experienced local bankruptcy attorney.
What Is the Chapter 13 Bankruptcy Process in Camden County?
To file for Chapter 13 bankruptcy in Camden County, New Jersey, start by completing the required credit counseling session within 180 days before filing. Next, gather the necessary financial documents and fill out the required bankruptcy forms, including your proposed repayment plan.

Submit these documents along with the filing fee to the U.S. Bankruptcy Court for the District of New Jersey. Once filed, attend the 341 Meeting of Creditors and participate in a confirmation hearing where a judge will decide whether to approve your proposed plan. Once confirmed, begin making payments as outlined in the plan to your Chapter 13 trustee.
Before you ever start the Chapter 13 bankruptcy process, seeking assistance from an experienced bankruptcy attorney is the best way to ensure your case is handled correctly. Luckily, the NJ debt relief lawyers at Sadek Bankruptcy Law Offices can walk you through every step of the process and ensure everything is done correctly and in accordance with U.S. bankruptcy law.
Top 25 Questions about Your Chapter 13 Bankruptcy
1. When do I start making my chapter 13 plan payments?
Your chapter 13 plan payments begin the month following the month in which your case is filed. For example if your bankruptcy is filed January 1, 2026, your first plan payment must be made February of 2026.
2. How do I make my Chapter 13 Plan payments?
There are several ways to make your Chapter 13 Plan payment. We will provide you detailed information on how to make payments, but briefly:
- You can make manual electronic payments online on your Trustee’s website using the “Epay” link;
- You can register with TFSBillPay.com to make either manual payments or to schedule how often you would like the payments deducted from your bank account or paystub;
- Our office can file a Wage Order with the Court which will allow your employer to deduct the payment from your paystub;
- You can mail payments to the Trustee via a secured P.O. Box, though this is not recommended for security reasons. If you must mail in payments, please note that we cannot guarantee the safe arrival of any payments mailed to the P.O. Box and strongly suggest that you use a tracking number.
3. What date is my Chapter 13 Plan Payment due?
The Chapter 13 Plan payment is due once per month. While the Bankruptcy Code states it should be paid by the first, as there are no late fees, penalties or interest that can accrue, there is no specific date the payment must be made by.
Please keep in mind that electronic payments can take 5-7 business days to process, be cleared and applied, so we strongly recommend that payments are made no later than the 15th of the month in which it is due. Please also keep in mind that payments made on a Friday, over the weekend or on a holiday will not be processed until the next business day. This can delay your payment being received by the Trustee. Therefore, be certain to make all payments in a timely manner to ensure that they are received and applied as quickly as possible.
If you are on a fixed income, such as Social Security or Pension, please make sure that your Chapter 13 Plan payment is made as soon as the funds are available.
4. What happens after I file?
The 341(a) Meeting of Creditors will be scheduled to be held approximately 30 days after your case is filed. This hearing is conducted via Zoom and you participate in this hearing. While you can be at work, you cannot be actively working. If you are in a vehicle it cannot be moving, even if someone else is driving. During the hearing the Trustee will ask you about your income, assets and expenses. They will also advise if any additional documents are needed. After the hearing, the Trustee will send our office a list of anything additional that is required or file an Objection to the Confirmation of your Plan. We will contact you regarding anything we need from you.
A Confirmation hearing will also be scheduled to be held approximately 45 days after your case is filed. You do not need to participate in this hearing as we will appear on your behalf if necessary. You must be current on your Chapter 13 Plan payments before the date of this hearing and all outstanding documents and/or amendments must be filed.
5. How can I see what Proofs of Claim have been filed in my case and what disbursements the Trustee has made?
You can access information regarding the Proofs of Claim filed by your Creditors, as well as payments you have made and how the funds have been disbursed at www.ndc.org.
6. If I was behind on my mortgage or car loan payments before filing, when do I resume making my mortgage and/or car payments after my case is filed?
You must resume your mortgage and/or car payments the 1st of the month following the month in which your bankruptcy is filed. For example, if your bankruptcy is filed January 1, 2026, your first car or mortgage payment must be made in February 2026 by the due date.
Note that if your payment is made after the contractual due date you will be liable for late fees. You are responsible for making your car loan and mortgage payments to the lender after the date of the filing of your case. If you fail to make timely payments, the lender will take action in your Bankruptcy.
7. If I am current on my car or mortgage, why do they have to be listed as creditors? And why can’t I pay them online anymore?
When a Bankruptcy is filed, all assets and all liabilities must be listed. This includes mortgages and car loans, even if you are current on the payments. Once the Automatic Stay goes into effect, none of your creditors can take any collection activity. This includes automatic deductions from your bank account for car and mortgage payments. Additionally, because online access to your car loan or mortgage account will list due dates, amount due and balance on the loan, this information may be construed as an attempt to collect on a debt. Therefore, the lender will most likely limit or even block your online access to account information and ability to make payments online.
8. If I cannot make payments to my mortgage or car loan online, what am I supposed to do?
Unfortunately, because the Automatic Stay is in effect as discussed above, you will most likely need to call your car loan or mortgage lender and make the payments by phone. In some cases, you may even be required to mail your payments. Please contact the lender and they will advise how to proceed.
9. Can my mortgage company charge fees after filing?
Yes, some mortgage companies will charge fees for retaining counsel to represent them in your bankruptcy. The lender can charge for their attorney to review your case, filing a proof of claim, drafting motions and other responsive pleadings that may need to be filed in your case. These amounts must be paid by you directly to the lender before the end of your bankruptcy.
10. Will my bankruptcy plan payment amount change?
It is possible that during the course of your bankruptcy, the plan payment as proposed at the time of preparation of your Petition and Plan may change. This can be caused by various factors including creditors’ claims coming in higher than anticipated, higher disposable income or excess equity in assets. If a change to your Plan payment is required, our office will discuss this with you in detail.
11. Can the IRS or State of New Jersey charge interest on taxes that are paid off in my bankruptcy?
Yes, the state or federal tax agency will calculate interest only through the date of the filing of your bankruptcy. Therefore, if they choose, after the discharge or successful completion of your bankruptcy they may notify you that interest remains due from the date of filing to the date of discharge. This amount will need to be paid directly to the taxing authority as it is not a part of the bankruptcy once discharged.
12. Can post-petition debt be included in my Chapter 13 bankruptcy?
No, post-petition debt, which is anything incurred after the date of filing, cannot be included in your Chapter 13 bankruptcy to either be paid or discharged.
Note that if your bankruptcy is converted from a Chapter 13 to a Chapter 7, then post-petition debts may be included in the converted case. In such cases, please advise our office of any post-petition debt so that we can review and discuss with you.
13. Can I finance a car or refinance my home while in bankruptcy?
Yes, but only with permission from either the bankruptcy Trustee or the Court. You must discuss this with our office before taking any action as the timing of the needed financing impacts how the matter would be handled. Please call our office for more details if you are considering financing a car or refinancing a home while in Bankruptcy.
14. Do I need to include all of my debts?
Yes, all creditors including credit cards, medical bills, personal loans and any other debt must be included on your bankruptcy petition. You will not be able to keep any of the credit cards for future use.
Please note that you must provide our office with all creditor information that is available to you. We are unable to obtain copies of medical bills, utility balances, MUA or property tax arrears, HOA arrears or other debts that are not reported on your credit report. If this information is not provided at the time of filing, you must do so immediately as certain priority debts may affect your Plan payment amount.
15. Why do I have to provide so much information, even after my case is filed?
All documents requested by our office are required by the Federal Bankruptcy Code as well as your Chapter 13 Bankruptcy Trustee. All documents must be provided to our office timely. If documents are not provided, your bankruptcy may be dismissed for failure to provide required information to the bankruptcy Trustee.
16. What if I fall behind on my Trustee payments or secured creditor payments such as my car or my mortgage during the course of my Bankruptcy?
If you fall behind on your Chapter 13 Plan payments or payments to secured creditors (such as mortgage or car loan), a Motion for Relief of the Automatic Stay or a Motion to Dismiss your case may be filed. If this occurs, our office will contact you to discuss how you intend to resolve the arrears. Please be advised that our office can take no action on your behalf without speaking with you. Therefore, it is imperative that you continue to provide our office with your most current phone number and email address, so we can contact you easily.
17. What happens if my financial circumstances change after my case is filed?
If your financial circumstances change, such as job loss or retirement, please contact our office to discuss the impact that this may have on your Bankruptcy. In some instances amendments may be needed that can allow for a change to your Plan payment or even possibly convert your case to a Chapter 7. If the change in circumstances is temporary, a motion may be filed to suspend or reduce Plan payments for a brief period.
Please contact our office so that we can assess the circumstances and determine the best course of action.
18. What happens if my Chapter 13 case is dismissed?
If your Chapter 13 case is dismissed for failure to make Chapter 13 Plan payments or failure to provide documents, our office will contact you with options in order to resolve the deficiencies or arrears. Options may include a Motion to Vacate Dismissal where feasible or a refiling.
If your case is closed without a motion to vacate the dismissal order, a new bankruptcy will need to be filed on your behalf. Additional fees and costs will be incurred.
19. Will I incur additional attorneys’ fees and costs during the course of my Chapter 13 bankruptcy?
It is possible that additional fees and costs may be incurred by our office during our representation of you. This can happen if our office is required to file motions on your behalf, such as selling property or requesting approval for a loan modification. Additionally, fees and costs can be incurred if our office is required to respond to motions filed by creditors in your case. This can include motions for relief of the automatic stay, Trustee’s motions to dismiss and certifications of default for failure to make plan payments. Fees incurred post-petition by our office can be included in your Plan payment or paid directly to our office with permission of the Court.
20. What if I win a lawsuit or receive an inheritance?
If you win money from a lawsuit, receive a settlement or receive an inheritance during the course of your Chapter 13 bankruptcy, you must notify our office. Any funds you may receive may not be fully exempt and therefore may be a part of the Bankruptcy Estate. This means that any windfall may need to be paid into your Chapter 13 Plan as an additional distribution to unsecured creditors.
21. Can I pay my Chapter 13 plan off early?
There are occasions where a Plan may be paid off before the proposed length of between 36 and 60 months. If this is something that you are considering, please notify our office so that we can discuss in more detail.
22. If I am filing a bankruptcy on my own, why does your office require information about my spouse or long-term partner’s income and expenses?
As per the Federal Bankruptcy Code, the United States Trustee’s Office and the Chapter 13 Trustee, proof of income for all contributions to the household must be listed on your Chapter 13 schedules, as well as overall household expenses. Therefore, even if you are filing an individual bankruptcy, your spouse and/or partner’s income and expense information is required to be provided. This is true even if you are not legally married to your partner.
23. Can I sell my house or other real property while in bankruptcy?
Yes, you can sell your house or other real property. The process is complicated and requires approval from the Bankruptcy Court. You cannot go to Settlement and Close on the property without a Court Order. Additionally, you will need to get approval for your realtor and any legal counsel you retain to represent you in the sale to be paid at the time of Closing. Therefore, we would ask that you contact our office as soon as you decide you want to proceed with the sale of the property.
Note that we do not represent you in the sale and do suggest that you retain real estate counsel to assist you with the process.
24. Can I request a Loan Modification or deferment from my mortgage company?
Yes, you can request a loan modification from your mortgage company while in Bankruptcy. If you are approved for a Final Loan Modification, a Partial Claim/Deferment or other such relief, you must notify our office immediately. A Motion for Approval of Final Loan Modification must be filed with the Court and, once approved, amendments to your Schedules and Plan will be required.
Therefore, please contact our office to discuss this matter in detail.
25. What happens when I am done making all of my Chapter 13 Plan Payments?
Once you have successfully completed making all of your required Chapter 13 Plan payments and the funds have been disbursed to creditors and cleared, the Trustee will issue a Plan Complete Letter. We will reach out to you at that time with detailed steps needed to finalize your Case. Once done, the Court will administratively review your matter and, if there are no outstanding issues, will issue your Discharge. The process from your last payment to the Discharge Order being issued by the Court can take several weeks.
Please note that while the above is a list of certain facts that may impact you and your Chapter 13 Bankruptcy, this is not a comprehensive list of all issues that may arise. Further, while online resources can be helpful, much information found via AI and other online sources is frequently incorrect. Additionally, every Debtor filing for Bankruptcy has different needs and requirements to make their case successful. Therefore, if you have any questions not addressed here, please contact our office to discuss in more detail.
How Can Our Chapter 13 Bankruptcy Lawyers Help You?
At Sadek Bankruptcy Law Offices in Camden County, NJ, our Chapter 13 bankruptcy lawyers provide comprehensive support to help you regain financial stability. With our in-depth knowledge of consumer and business bankruptcy law, we’ll thoroughly assess your financial situation to determine if Chapter 13 is the most suitable option. Then, our attorneys will assist in preparing and filing all necessary documents with the bankruptcy court, ensuring accuracy and compliance with legal requirements.
We can aid in developing a feasible repayment plan tailored to your circumstances and represent you in court proceedings, including the Meeting of Creditors and confirmation hearings. Throughout the repayment period, an NJ bankruptcy attorney on our team will offer you ongoing guidance to help you adhere to the plan and address any arising issues, aiming to protect your assets and achieve financial freedom.
Schedule a Free Consultation with a Camden County Chapter 13 Attorney
If you’re struggling with overwhelming debt and need a solution that allows you to protect your assets while regaining financial stability, our team at Sadek Bankruptcy Law Offices is here to help. Filing for Chapter 13 bankruptcy can be a complex process, but with the guidance of an experienced NJ bankruptcy attorney, you can create a repayment plan that works for your unique financial situation.
Take the first step toward a fresh start by scheduling a free consultation with a trusted NJ bankruptcy attorney at Sadek Bankruptcy Law Offices. We serve a variety of areas in Camden County, including Berlin, Collingswood, Gloucester City, Pennsauken, Voorhees, Winslow, and more. Additionally, we have an office in Cherry Hill.
We offer free initial consultations to all new clients, so call our law firm at (856) 890-9003 or contact us online to schedule today.
To arrange a free and confidential consultation with a Philadelphia bankruptcy attorney regarding your legal matter, call our Philadelphia headquarters at 215-545-0008.
Work with Our Dedicated and Experienced Bankruptcy Lawyers
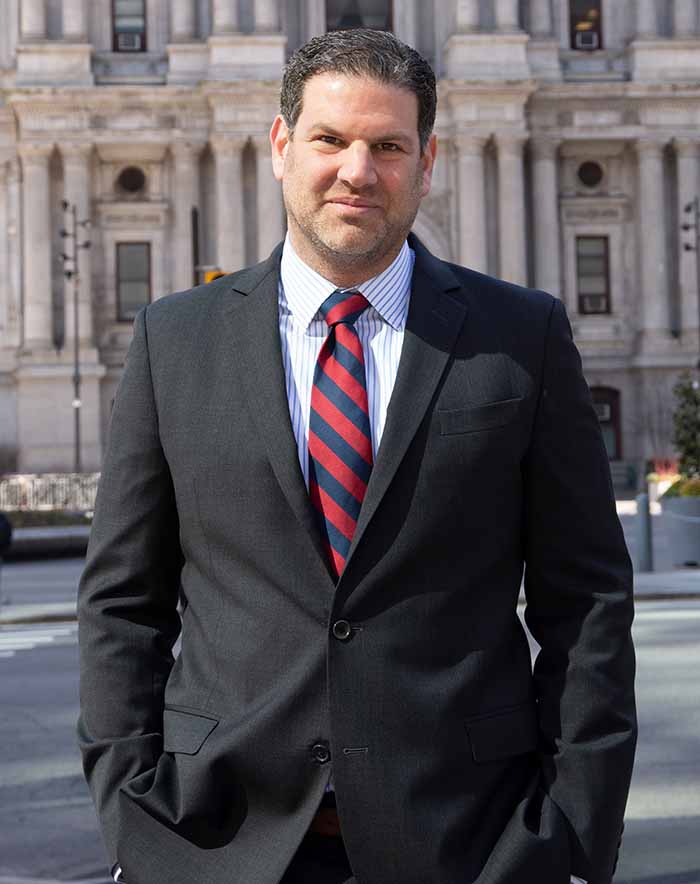
Sadek Bankruptcy Law Offices, LLC has a dedicated team of lawyers who help clients achieve the benefits of bankruptcy in Pennsylvania and New Jersey. Our lawyers have over 75 years of combined experience and have filed more than 5,000 successful bankruptcy cases.